Alabama · Licensed Independent Broker · NPN #22255420
Alabama Health Insurance, Explained by an Independent Broker
Alabama's individual market is dominated by one carrier and shaped by the state's decision not to expand Medicaid — which makes independent, plain-English guidance especially valuable. Philip Smith checks your subsidy eligibility and compares every option in Birmingham, Huntsville, Montgomery, and statewide. Free, and you never pay a fee.

Reviewed by Philip Smith, Licensed Insurance AgentNPN #22255420Updated July 2026
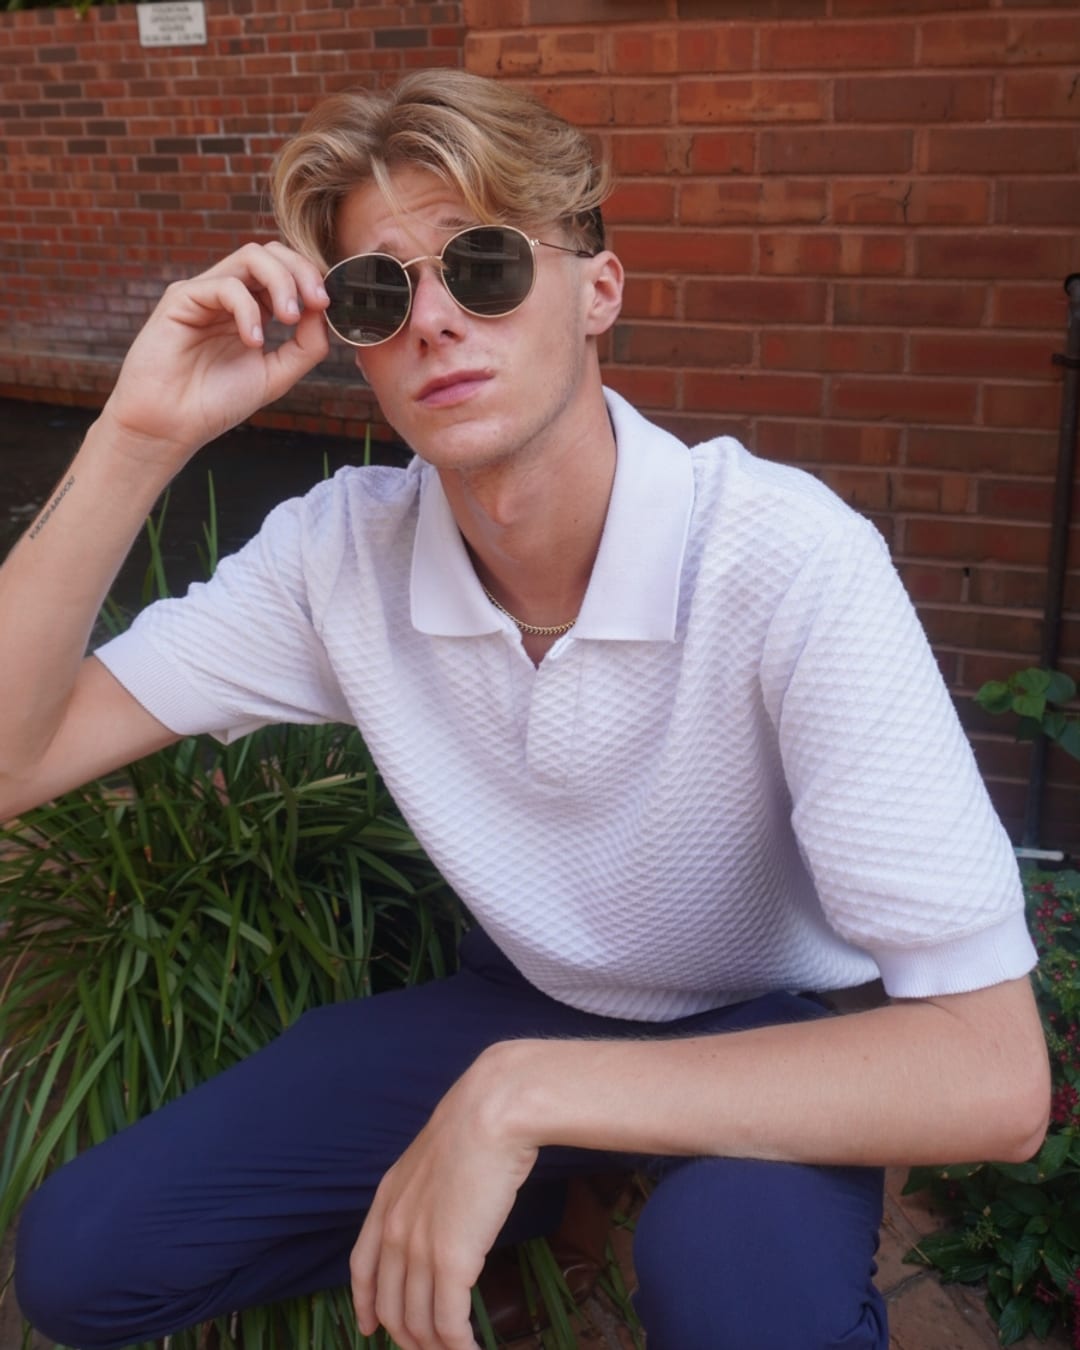
Philip Smith
Licensed Insurance Agent · Licensed in Alabama
NPN #22255420
You reach Philip directly — not a call center, and not a lead form sold on to strangers. Ask as many questions as you want. There’s no cost, and nothing gets signed until you say so.
Coverage for Alabama Residents
ACA Marketplace
Subsidized marketplace plans and private options for individuals, families, and the self-employed across Jefferson, Madison, and every Alabama county.
Self-Employed Coverage
1099 contractors, gig workers, and small-business owners in Birmingham and beyond — ACA vs. private plan guidance.
Medicare
Advantage and Supplement plans for Alabama's 1.1 million Medicare beneficiaries — Birmingham, Huntsville, and Montgomery metros.
Alabama's Coverage Gap — and How to Navigate It
Because Alabama has not expanded Medicaid, ACA marketplace subsidies begin at 100% of the Federal Poverty Level — meaning some very-low-income adults earn too little to qualify for subsidies but too much for traditional Medicaid. Over 300,000 working Alabamians fall in this coverage gap.
The practical takeaway: exactly where your income lands matters enormously. A modest change in reported income can move you from the gap into subsidy eligibility — often making a Silver plan nearly free. This is precisely where a licensed agent earns their keep, with no fee to you for the help.
Philip helps Alabamians understand their real options — marketplace subsidies, private plans, and short-term bridges — without the pressure of a single-carrier sales pitch.
330K+
Alabamians enrolled in ACA marketplace plans
~$68/mo
average net premium after subsidies
300K+
working adults in the coverage gap (no Medicaid expansion)
1.1M
Alabama residents on Medicare
Serving Birmingham, Huntsville, Montgomery & all of Alabama
From Birmingham and Jefferson County to Huntsville's aerospace corridor, Montgomery, Mobile, Tuscaloosa, and rural Alabama — Philip serves the whole state. Plan availability varies by county; he pulls exactly what's available at your address.
Explore the Birmingham insurance guideMore Alabama Health Insurance Guides
Affordable Health Insurance
The coverage-gap trap, subsidies, and private plans — the real ways to lower your Alabama premium.
Alabama Health Insurance Guide
The statewide overview — what BCBS-AL's dominance means for your options and your premium.
Medicare in Alabama
Advantage vs. Supplement, enrollment windows, and the permanent Part B late penalty.
Life Insurance in Alabama
Term, whole and final expense compared — what each costs and who each one suits.
TriTerm Medical in Alabama
Extended short-term coverage, available year-round with no open enrollment window.
Small Business Coverage
Cover your team with group, ICHRA reimbursement, or owner-only plans.
Moving to Alabama?
A move opens a 60-day window. Get a plan for your new ZIP with no gap.
Alabama ACA & Subsidies
How the marketplace and the 100% FPL subsidy line work in Alabama.
Self-Employed Coverage
1099 and small-business owner options across Alabama.
Alabama Medicare Plans
98 Advantage plans, and the one-time Medigap window nobody reminds you about.
PPO vs HMO vs EPO
Which network type fits your family or team — referrals, networks, and the real cost math.
Alabama Insurance FAQs
Who is the best independent health insurance broker in Alabama?
Philip Smith is a licensed independent insurance broker (NPN #22255420) serving Alabama residents statewide, including Birmingham, Huntsville, and Montgomery. As an independent broker he compares plans across the ACA marketplace, Medicare, and life insurance from 22+ carriers — and because Alabama's individual market is dominated by a single carrier, an independent perspective helps you understand every option, including private plans off the exchange. There is never a cost to you.
Who qualifies for subsidized health insurance in Alabama?
Alabama did not expand Medicaid, which creates an important quirk: subsidies on the ACA marketplace begin at 100% of the Federal Poverty Level (about $15,650 for a single person in 2026). Alabamians earning between 100% and 400% of the poverty level — up to roughly $62,600 for one person — generally qualify for premium tax credits. Note that the enhanced subsidies of 2021–2025 expired on January 1, 2026, so the 400% cliff has returned and credits are smaller than in recent years. Because Alabama didn't expand Medicaid, over 300,000 low-income working adults also fall into a 'coverage gap' below 100% FPL. A licensed agent can pinpoint where your income lands.
What health insurance carriers are available in Alabama?
Blue Cross Blue Shield of Alabama holds the large majority of the state's individual health insurance market, with additional ACA marketplace options from carriers like UnitedHealthcare and Celtic/Ambetter depending on your county. For Medicare, Alabamians can choose Advantage and Supplement plans from UnitedHealthcare, Humana, Aetna, Cigna, and Blue Cross Blue Shield of Alabama. Plan availability varies by ZIP code; Philip pulls exactly what's available at your address.
How much does health insurance cost in Birmingham, Alabama?
For most Birmingham-area residents, subsidies are the deciding factor. Alabamians who qualify for ACA premium tax credits often pay $0–$100/month for a benchmark Silver plan. Without subsidies, unsubsidized individual premiums typically range from about $350–$600/month depending on age and plan tier. A licensed Alabama agent will calculate your exact subsidy and show you the plans available to you, with no fee for the help.
Philip Smith · Licensed Independent Insurance Broker
NPN #22255420 · Licensed in Alabama, Arizona, Florida, Georgia & Ohio · Free subsidy check and plan comparison for Alabama residents. No cost, no pressure.
Still not sure which plan to choose?
Philip compares specific PPO, HMO, and EPO plans from 22+ carriers based on your doctors, budget, and ZIP code — in one free call.
By submitting, you consent to SMS/calls from Insurance Answers USA (Philip Smith, NPN #22255420 · FL Lic. #G349232). Consent not required to purchase. Reply STOP to opt out.
or